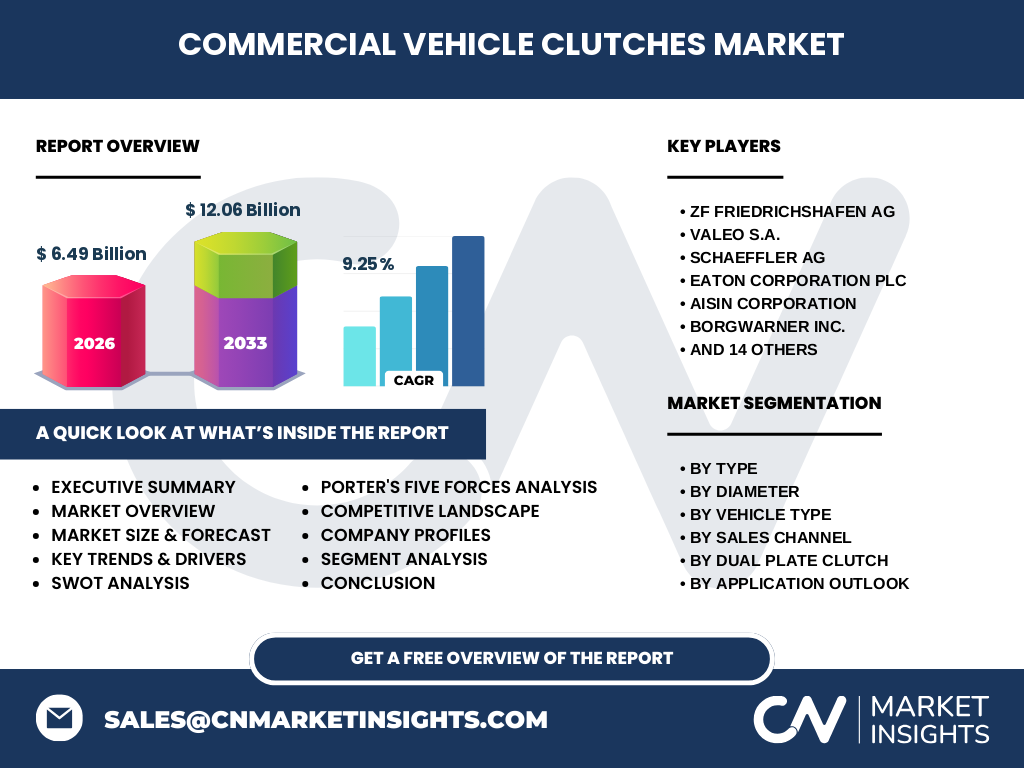
What is the market overview of the Commercial Vehicle Clutches Market?
Our analysis indicates the Commercial Vehicle Clutches Market represents a critical powertrain component sector encompassing single and dual-plate systems for light, medium, and heavy-duty trucks, buses, and off-highway machinery. Valued at $6.49 Billion in 2026, this industry governs torque transmission and gear shifting efficiency across global logistics networks.
Structural Growth Drivers and Restraints in the Commercial Vehicle Clutches Market
The market is propelled by strict emissions mandates from bodies like the EPA and Euro VII, forcing fleet operators toward advanced Automated Manual Transmissions (AMTs). Conversely, supply chain bottlenecks for high-grade friction materials such as sintered bronze and organic composites act as primary operational restraints.
Emerging trends and growth patterns in Commercial Vehicle Clutches Market
A definitive shift toward wet dual-plate clutches is underway, designed to handle higher torque density demanded by long-haul electric and hybrid heavy-duty trucks. Manufacturers are integrating smart sensors into clutch actuation systems to predict wear cycles and minimize total cost of ownership for fleet managers.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and temporary shutdowns across major OEM assembly plants in Europe and North America. However, the subsequent post-lockdown logistics surge triggered an aggressive V-shaped recovery, rapidly escalating demand across both OEM and aftermarket channels.
Competitive benchmarking and strategic dynamics
The industry features intense rivalry among tier-one heavyweights like ZF Friedrichshafen AG, Valeo S.A., and Schaeffler AG. Companies are leveraging localized manufacturing hubs near major logistics ports to mitigate freight volatility and secure long-term supply contracts with truck original equipment manufacturers.
Executive summary of the Commercial Vehicle Clutches Market industry trends
Driven by robust infrastructure investments and tightening fuel economy standards, the Commercial Vehicle Clutches Market is poised for exceptional expansion. Our research projects the market to surge from $6.49 Billion in 2026 to $12.06 Billion by 2033 at a remarkable 9.25% CAGR.
Commercial Vehicle Clutches Market forecast from 2027 to 2033
The forecast period highlights sustained momentum, advancing at a 9.25% CAGR to reach $12.06 Billion by 2033. This growth is underpinned by rising commercial freight volumes across emerging economies and the continuous adoption of 430mm heavy-duty clutch assemblies in long-haul trucking.
Segmentation analysis of the Commercial Vehicle Clutches Market
Segmentation spans vehicle types including light commercial vehicles, medium and heavy-duty trucks, buses, and off-highway machinery. Sales channels split between OEM installations and aftermarket replacements, while diameter specifications range from 280 millimeters up to 430 millimeters to accommodate varying engine torque outputs.
Regional market analysis and geographic distribution
Geographic performance reflects heavy industrialization and stringent regulatory frameworks. Asia-Pacific dominates volume production due to massive commercial vehicle output in China and India, whereas North America and Europe prioritize advanced automated manual transmission clutches to meet rigorous carbon emission standards.
In-depth regional review of key manufacturing hubs
In North America, strict EPA greenhouse gas standards drive fleet modernization toward high-capacity 400mm and 430mm clutches. Meanwhile, Europe relies heavily on advanced mechatronic integration by suppliers like Eaton Corporation plc and ZF Friedrichshafen AG to optimize fuel efficiency across cross-border freight corridors.
Company profiles and strategic market positioning
Market leaders such as AISIN Corporation, BorgWarner Inc., and EXEDY Corporation focus on proprietary friction material R&D to enhance thermal resistance. Regional specialists like Setco Automotive Limited and Brakes India Private Limited capture high-growth aftermarket share through extensive domestic distributor networks.
Porter's Five Forces analysis of the sector
Supplier power remains moderate due to specialized raw material requirements for friction facings. Buyer power is high among massive truck fleet operators who demand competitive pricing, while threat of substitution is mitigated by the ongoing dominance of internal combustion and hybrid commercial powertrains.
SWOT analysis of the Commercial Vehicle Clutches Market
Strengths lie in robust mechanical engineering and established OEM partnerships. Weaknesses involve vulnerability to steel and friction material price fluctuations. Opportunities abound in the electrification transition via wet dual-plate systems, while threats include rapid EV adoption reducing long-term manual transmission demand.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material extraction—procuring steel, organic resins, and copper fibers. Tier-1 suppliers forge, assemble, and test finished clutches before shipping to OEM assembly lines or regional aftermarket distributors who supply commercial fleet repair depots.
Investment insights and high-potential areas
Strategic investments should target automated manual transmission clutch components and wet dual-plate technologies. Stakeholders should focus capital allocation toward Asian manufacturing hubs and R&D facilities specializing in lightweight, thermally efficient friction linings for heavy-duty applications.
Conclusion and key takeaways for stakeholders
The Commercial Vehicle Clutches Market market size expansion to $12.06 Billion by 2033 underscores the vital need for technological adaptability. Companies investing in advanced AMT integration and robust aftermarket distribution will capture outsized returns during this forecast period.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from global automotive associations. This multi-layered approach ensures precise market sizing and growth validation.
Scope of the report and coverage parameters
This report covers global market dynamics for commercial vehicle clutches from 2026 to 2033, analyzing segments by diameter, vehicle type, sales channel, and application. Limitations include unforecasted macroeconomic shocks and localized trade policy shifts affecting raw material imports.
Recent developments and strategic industry moves
Recent milestones feature joint ventures by major entities like Eaton Cummins Automated Transmission Technologies to launch next-generation automated clutches. Concurrently, Schaeffler AG and Valeo S.A. have expanded production lines for heavy-duty wet clutches to support surging demand from commercial fleet operators.